We built Saarathi because small-business credit is a solvable gap.
The data to assess a micro-business borrower has long existed. Lenders lacked a system to interpret it quickly enough to matter.
Why we began.
In India, NBFC credit managers spend hours manually reviewing cash flow for each SME application. They collect bank statements, examine transactions, mark overdraft dates, and estimate income stability. The work demands care, though a model that understood the signals could complete much of it in minutes.
Saarathi began with a straightforward insight: bank statements and GST data hold enough structure to score a micro-business borrower as reliably as, or more reliably than, a credit analyst conducting a full manual review. The issue was not missing data. It was missing infrastructure to process it at the pace an active NBFC lending program needs.
We built Saarathi as that infrastructure: an API an NBFC can connect to its loan origination system in one day. It reads 90 days of cash-flow data, GST compliance history, UPI transaction patterns, and invoice records, then returns a credit score and written narrative in under three minutes. It delivers the analysis of a strong credit analyst at the scale and speed your portfolio requires.
Our team.
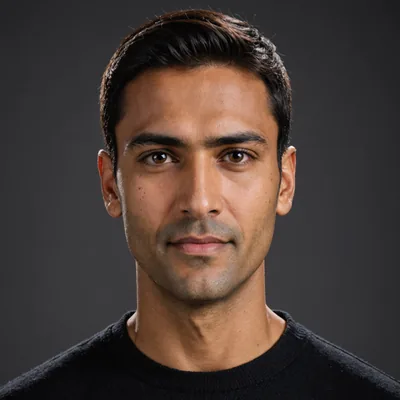
Vivek Bansal
CEO & Co-Founder
Vivek spent years in credit risk strategy and underwriting operations across regional NBFC lending programs before moving into fintech product. He saw how much time credit managers devoted to manual cash-flow extraction and built Saarathi to automate that work while preserving the explainability credit committees require.
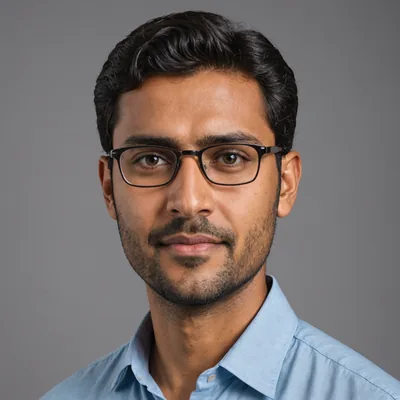
Arjun Mehta
CTO & Co-Founder
Arjun has spent his career building credit scoring pipelines and alternative data APIs for financial lending platforms. His machine learning and data infrastructure background informs Saarathi's core architecture, especially the feature engineering layer that turns raw financial records into structured credit signals.
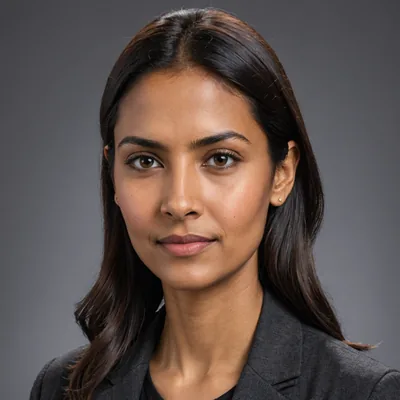
Priya Nair
Head of Credit Science
Priya joined Saarathi after working in NBFC underwriting and quantitative credit assessment. She leads model validation and signal research, identifying which alternative data features genuinely predict Indian SME credit risk and which are noise.
What guides us.
Borrower-first choices
The SME applicant, not the lender's legacy system, is the person we aim to help. We test every product decision by asking whether it helps a creditworthy borrower get approved faster.
Score transparency
Every output carries its reasoning, not only a number. A score without an explanation does not help a credit committee. Every score we return must be explainable.
Built independently
Saarathi is independently funded. We do not have pressure to grow before the product is ready. That freedom keeps our focus on a model that performs well across real NBFC portfolios before we expand.